
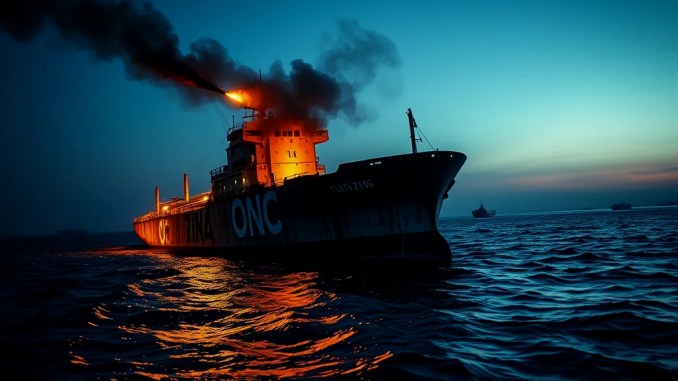
In October, the Strait of Hormuz and nearby waters recorded an unprecedented spike in attacks on commercial vessels, with monitoring groups confirming 28 incidents — the highest monthly total since 2017. These attacks have constricted ship movements through one of the world’s most important oil transit chokepoints and pushed market indicators and routing decisions to adapt rapidly.
October’s 28 Verified Incidents and What They Reveal
Researchers tracking maritime security since 2017 verified or received reports of 28 attacks in the Strait and adjacent waters during October. That figure reflects concentrated operational pressure around the strait in September–October and signals an escalation compared with previous months. Aggregated incident tallies vary by source because of differences in geographic scope and reporting methodologies: Washington Institute researchers counted 113 incidents affecting the area since the conflict expanded after February 28, while International Maritime Organization (IMO) data covering a broader Middle East region lists 120 incidents over the same period.
Cross-referencing IMO records with ship-tracking datasets shows more than 30 very large crude carriers (VLCCs) sustained damage since hostilities began; 11 of those were hit in October alone. Given the global VLCC of roughly 900 ships, that damage accounts for about 3.5% of that segment — a material hit to available very large crude transport capacity when each VLCC can carry on the fleet of 2 million barrels.
How Reduced Traffic Through the Strait Translates to Supply Risk
Market assessments published on October 27 put vessel transits through the Strait at about 60% of normal levels — a roughly 40% drop in passage activity. That decline stems from multiple, observable behaviors: owners reroute ships where possible, operators suspend automatic identification system (AIS) transmissions for security, and certain cargoes shift to land or alternative maritime corridors. Each response reduces the visible traffic baseline and can increase effective delivery times.
Importantly, reduced transit counts do not translate one-to-one into equivalent declines in Gulf crude exports. Shippers have used pipeline alternatives, transshipment via ship-to-ship (STS) transfers, and different export terminals to maintain flow. Still, these workarounds carry higher operational cost and capacity limits — and they cannot fully offset the loss of straightforward, high-throughput seaborne routes through the Strait.
Price Impacts: Brent Above $116 and the Channels of Influence
On October 27 at 10:18 TRT, Brent traded at $116.24 per barrel (+0.4%), and WTI registered $102.07 (+0.3%). Prices climbed after intraday softening because persistent attacks kept risk premium elevated. A simple mechanism explains the reaction: elevated transit risk raises the probability of supply disruption or delayed deliveries, which markets price immediately into forward curves and physical spreads.
Additional structural pressure comes from low product stocks: global middle distillate inventories ran roughly 5% below their five-year average, amplifying the upside sensitivity to any crude delivery hiccup. Higher freight rates, conflict-zone insurance premiums, and the operational friction of rerouting all add to delivered-cost uncertainty and can sustain higher spot levels even if nominal export volumes do not fall proportionally.
Operational and Insurance Costs: The Hidden Multipliers
Commercial players face measurable cost multipliers when operating through higher-risk passages. Examples and steps operators take:
Re-routing: Diverting around risk zones increases steaming time and fuel burn. For example, rerouting from the Strait of Hormuz can add days to voyages using longer approaches through the Cape of Good Hope, implying additional voyage fuel costs, a later arrival window, and cascade scheduling impacts on charterers.
Ship-to-ship transfer (STS): Operators move crude offshore between vessels or into shuttle tankers to bypass chokepoints. STS reduces terminal dependence but requires specialist crews, tugs, and safe-anchorage infrastructure, which raises hourly operational expense and limits throughput rates.
Insurance and war-risk premiums: Carriers in high-risk waters pay higher war-risk cover and kidnap/ransom endorsements. These premiums can transform a voyage’s economics, influencing the choice between carrying Atlantic-bound crude by sea or shifting to pipelines where feasible.
Diplomacy and Regional Dynamics That Markets Watch
Diplomatic engagement continued as regional states pursued de-escalation tracks. On October 26, delegations from Saudi Arabia, Turkey, and Pakistan met Iranian officials in Tehran and reported agreement to continue contacts on regional security and cooperation. Markets track such meetings because they can reduce tail-risk and restore predictable transit patterns.
At the same time, Iran-aligned Houthi activity against Saudi Arabia and concurrent risks in the Red Sea complicated recovery routes. Simultaneous disruptions across multiple maritime corridors compress available rerouting options, forcing shippers to weigh longer detours against uncertain throughput at alternative terminals.
What Shippers, Traders, and Policymakers Should Do Now
Stakeholders can apply targeted, practical responses to limit disruption and cost spikes:
For shippers: Increase voyage contingency buffers in scheduling, pre-contract additional bunkers for likely longer passages, and favor charter terms that allow flexibility for route changes without punitive clauses.
For traders: Hedge incremental physical exposure where transits concentrate; Seek shorter-dated forward coverage to reflect evolving local risk premium and utilize cross-hemisphere arbitrage to maintain supply continuity when route premiums diverge sharply.
For policymakers: Expand surveillance and escort cooperation for commercial convoys, facilitate rapid approval for temporary STS zones under safe surveillance, and coordinate with insurance markets to stabilize war-risk pricing via transparent risk-sharing frameworks.
Short-Term Outlook and Key Indicators to Monitor
Near-term market direction depends on three measurable variables:
1) Incident frequency — a sustained decline in verified attacks should restore some owner confidence and reduce insurance premiums. Watch weekly incident tallies from independent maritime monitors and IMO updates.
2) Transit throughput — AIS-derived transit counts through the Strait provide a real-time proxy for operational flow. Recovery toward pre-conflict averages would signal lower disruption risk.
3) Inventory and freight spreads — Middle distillate stock levels and freight differentials between secure and at-risk routes indicate how tight physical markets are and how much routing costs push incremental prices.
If hostilities ease and diplomatic channels sustain, expect a gradual normalization of transits over weeks to months. If attacks persist or expand, expect continued upward pressure on spot crude and product prices, higher freight rates, and prolonged reliance on higher-cost routing and transfer operations.
In sum, October’s spike in attacks across the Strait of Hormuz introduced tangible supply friction that markets, shippers, and policymakers must manage through adaptive routing, contractual flexibility, and coordinated risk-mitigation measures. Close monitoring of incident counts, transit metrics, and inventory balances will determine whether the impact remains a near-term shock or evolves into a structural premium on Gulf crude exports.
Be the first to comment